HomeStretch: Program Recap
HomeStretch is a Shared Equity Loan Program that NeighborWorks Montana launched this past year in an effort to expand access to homeownership lending. A HomeStretch loan contributes up to 30% of the cost of the home. In exchange, eligible borrowers agree to an equity cap at time of sale. Repayment of contribution is deferred until repayment trigger, such as the sale of the home. Funding for the program is a partnership between Community Reinvestment Organizations, State funding and private investment.
In the first year of HomeStretch the program was able to assist 90 households through homeownership loans. The median loan amount was $87,928 and the total dollar deployed across the ninety loans is $7,913,518. The primary users of this loan product are working people in the state of Montana with careers in the trades, healthcare, and public service. Borrower professions range from carpenters and electricians to registered nurses, gas station managers, and car salesmen.
“We had to move for more space for our family to exist. When we looked into a larger rental, we realized that the cost per month was similar to a mortgage, but we didn’t really know how to go about looking for a house,” explained Breanna and Trenton, new HomeStretch homeowners.
“The fact that they offered so much down payment assistance was the big deciding factor. There’s no way we would be able to afford anything in the near future without that assistance. We looked at a few other options but they just didn’t fit with what we wanted and needed for our family.”
As the program is in its infancy, we can say that the 90 loans deployed in a year is evidence of its need and a marker of success. The first year also included challenges.
Program Challenges
Borrower Fit: 30% Front End Ratio coupled with the max AMI of 140% makes homes difficult to find in higher cost markets and equity share is restrictive.
Serving all Counties: It is difficult to serve counties with higher cost markets. So what we see is very little (or no) allocation in some counties and exceptional allocation in others.
Counseling: Ensuring the equity share is understood by borrowers is a top priority and has required highly trained counselors and ongoing lender and realtor outreach.
Program Complexity: Navigating misunderstandings including confusion about equity share and confusion about different models with NWMT / NWGF and HAB
Looking Forward
Looking forward into the next year of HomeStretch we hope to do continued outreach, education, and strengthen our partnerships. To mitigate some of the challenges we are considering requesting the followings legislative changes:
- Allow County AMI rather than State AMI
- Allow higher borrower equity share
- Increase flexibility in the debt to income ratio
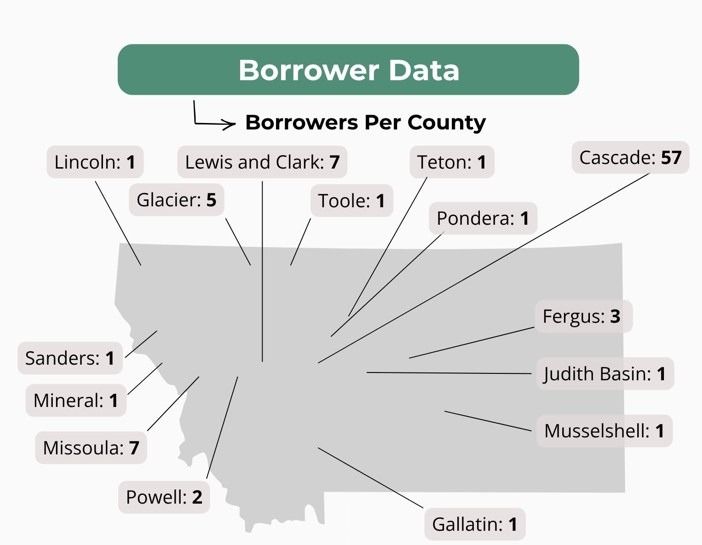
Borrowers per county, more data in the report linked below.
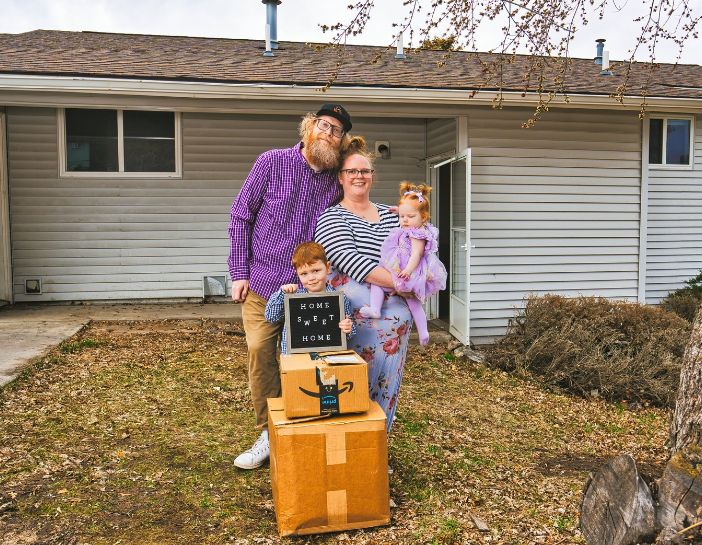
Breanna and Trenton outside of their home!
